

BILL AP & AR Business Payments analysis by Appwee
When a small business starts paying suppliers and collecting customer money through separate tools, the work can become harder than the transactions themselves. I tested BILL AP & AR Business Payments with that situation in mind: one place intended to help a company manage outgoing bills and incoming payments online. My overall impression is that it makes the most sense for teams that want a more organized payment workflow, not for someone looking for a simple personal bill-paying app.
The app sits in the business category and comes from Bill.com Inc. It is free to download, suitable for Everyone, and has built a solid audience with over 500 thousand installs. Its average rating is 4.3 from around 7.5 thousand ratings, which suggests that many users find the general workflow useful, while the experience may still depend heavily on how well it fits a company’s existing habits.
From an unpaid bill to a completed business payment
The starting condition: payment work scattered across the business
The clearest way to understand this app is to imagine a small design agency after a busy week. An invoice from a freelance editor arrives, a software supplier sends a recurring bill, and a client needs to pay for completed work. Without a dedicated process, the owner may keep invoices in email, payment details in a spreadsheet, approval messages in chat, and bank activity in a separate portal.
BILL AP & AR Business Payments is designed around bringing the accounts payable and accounts receivable sides closer together. In plain language, that means handling money the business owes and money the business expects to receive within the same business-focused environment. That combined perspective is its most useful idea.
I would not describe it as a replacement for every accounting task. Instead, I see it as a payment-workflow layer. It can help turn a loose collection of invoices and payment requests into a sequence: identify the obligation, review it, send or receive the payment, and keep the result connected to the business process.
That distinction matters before installing it. If you only need to split a household bill or send money to a friend, this is far more business-oriented than necessary. If you regularly manage vendors, customers, approvals, and payment follow-up, the focus becomes much more relevant.
Step one: bringing a bill or payment request into view
The first practical benefit is visibility. A bill that stays buried in an inbox is easy to overlook, especially when the person who receives it is not the person who approves or pays it. A business payment app is valuable when it gives the team a clearer starting point than searching through email every time something needs attention.
My advice is to treat the initial entry as an accuracy checkpoint rather than a formality. Check the supplier or customer, the amount, the due date, and the reason for the transaction before moving forward. Payment tools can make a process neater, but they cannot correct an incorrect invoice or a rushed data entry decision.
This is also where the app’s accounts payable and accounts receivable split becomes useful. An outgoing supplier bill and an incoming customer payment may look similar on a screen, but they lead to different responsibilities. One needs a payment decision; the other needs collection and reconciliation. Keeping those directions distinct helps reduce the chance of treating every transaction as the same kind of task.
A less obvious advantage is that the workflow encourages the user to think in terms of status rather than memory. Instead of asking, “Did I deal with that invoice?” the better question becomes, “Is it waiting for review, ready to pay, or completed?” That small change can be valuable for a business owner who is handling finance between sales calls and operational work.
Step two: reviewing before money moves
The review stage is where a business should slow down. I would use it to confirm that the transaction belongs to the company, that the amount matches the supporting document, and that the recipient information is correct. This is especially important when several people share responsibility for payments.
For a very small company, the owner may perform the whole process alone. In a growing team, the person who receives an invoice may be different from the person who authorizes payment. That handoff is not a minor detail: it is the point where a convenient app must fit the company’s internal trust and approval habits.
The app is most helpful when it gives people a common place to work from, but users should not assume that centralization automatically creates good controls. A business still needs a simple rule for who checks invoices, who approves unusual amounts, and who follows up on overdue customer payments.
I found this particularly relevant for recurring expenses. A familiar supplier can create false confidence, and a repeated bill may receive less attention than a new one. A quick review of the actual invoice remains worthwhile. Convenience should reduce forgotten work, not remove judgment from the process.
Step three: completing the outgoing or incoming side
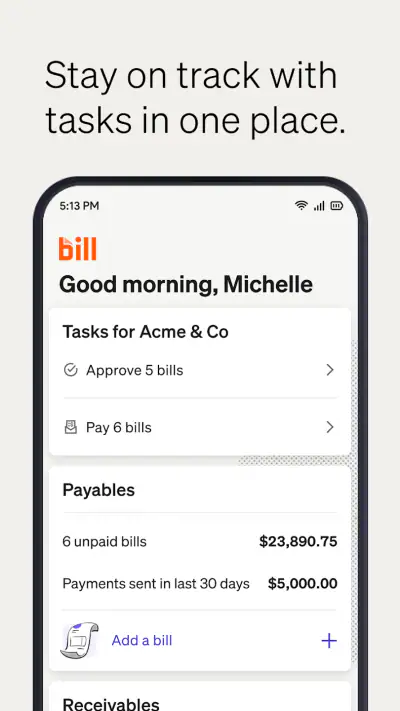
Once the details are checked, the workflow moves toward its outcome: paying a business bill or helping the company get paid online. This is the point at which the app’s purpose is clearest. Rather than using one tool for accounts payable and another for accounts receivable, a business can approach both sides through the same general payment platform.
For outgoing payments, the useful question is not merely whether the payment can be sent. It is whether the team can understand why it is being sent, who handled it, and what still needs attention afterward. For incoming payments, the question changes to whether the company can connect the customer’s payment with the original obligation and stop treating the invoice as open.
That difference makes the app more suitable for operational finance than for casual transfers. It is aimed at the surrounding process, not just the moment when money changes hands. I would recommend setting aside a regular review period so completed transactions do not disappear into the background while unresolved items accumulate.
A practical tip is to separate urgent exceptions from normal scheduled work. A supplier threatening to pause service deserves a different response from a routine monthly bill. Likewise, a customer who has missed a payment needs follow-up rather than simply being left in a general queue. The app can support a structured process, but the business still has to decide which items deserve immediate attention.
The handoffs that determine whether the workflow works
Payment software is often judged by the person clicking the final button, but the handoffs before and after that action are just as important. A bookkeeper may enter or review a transaction, an owner may approve it, and another team member may need to confirm that the supplier or customer relationship is up to date.
In my view, this is where a business should test the app before committing to it as a central process. Ask who will open the transaction, who will check the details, who is allowed to authorize it, and who will investigate a payment that does not appear to have completed. If those answers are unclear, the software will not solve the underlying confusion.
The accounts receivable side adds another handoff. Sales may promise a customer a payment schedule, finance may monitor the invoice, and management may need to know when cash is late. A payment platform can bring the financial task into focus, but it cannot replace communication between those roles.
For a solo operator, fewer handoffs are a genuine strength. The same person can see the bill, make the decision, and check the result. For a larger organization, the app may be more useful when paired with clearly written internal procedures. Without that structure, a shared system can still become a crowded place where everyone assumes someone else is handling the next step.
What the result looks like in everyday use
Return to the design agency example. The editor’s invoice is reviewed and moved through the outgoing payment process. The software supplier’s recurring charge is checked instead of being paid automatically from memory. The client’s payment is handled as an incoming transaction, giving the owner a clearer view of what has arrived and what still needs attention.
The result is not simply “three payments completed.” The better result is a more understandable financial day. The owner can spend less time reconstructing events from scattered messages and more time deciding what needs action. That is the real reason I would recommend trying this app: it can make payment work feel like a process rather than a series of isolated chores.
It is also useful for a business that has outgrown informal habits but is not ready to build a complicated finance operation. A small consultancy, agency, contractor, or service company may benefit from having a dedicated business payment workflow before its transaction volume becomes difficult to manage manually.
Still, organization is not the same as accounting completeness. I would continue checking the business’s broader financial records and use the company’s established accounting practices alongside the app. The payment workflow should produce clearer activity, but the business remains responsible for reviewing its books and making sure transactions are properly handled.
Where the flow breaks down
The first limitation is that this is not a universal solution for every payment situation. A person who only wants to pay personal bills will probably find the business framing unnecessary. It is also not the best choice for someone who wants a minimal interface with no distinction between payable and receivable work.
The second friction point is process discipline. If invoices arrive through many channels and nobody agrees on where they should be reviewed, adding an app can create one more place to check rather than a single source of truth. Before using it seriously, I would decide how the team submits bills and how customer payment information is communicated.
Another trade-off is the learning curve that comes with business context. A user has to understand the difference between paying a supplier and collecting from a customer, as well as the handoffs around approval and follow-up. That is sensible for a business tool, but it may feel heavier than a basic bank app.
I would also be cautious about choosing it solely because it is free to download. The important question is whether the workflow matches the company’s needs and whether the people involved will actually use it consistently. A free app that nobody checks is less valuable than a familiar process that the team follows every day.
The current version is 3.7.171, and the app supports iOS 9 or later. That makes checking device compatibility a sensible first step for anyone using an older iPhone or iPad. On a supported device, I would still begin with a small, low-risk workflow rather than moving every business payment into the app immediately.
Who should use it, and who should choose another route?
I think it is a good fit for small businesses that need to manage both vendor bills and customer payments, especially when the owner or finance person is tired of switching between email, bank tools, and informal tracking. It can also suit a team that wants clearer handoffs without starting with an overly elaborate finance system.
It is less suitable for personal finance, one-off payments, or a company whose needs are already deeply tied to a different accounting and enterprise payment setup. In those cases, a tool built around the existing accounting environment may reduce duplicate work more effectively.
It may also be the wrong choice if the business has no defined approval process. The app can help expose pending work, but it cannot decide whether a bill is legitimate, whether a customer deserves a reminder, or whether a payment should be held for review. Those decisions require people and policies.
Before adopting it, I would run a short trial using ordinary transactions: one supplier bill, one recurring expense, and one customer payment. Watch where information enters, who has to intervene, and how easily the team understands the final status. That test will reveal more than a quick look at the download screen.
My recommendation after following the full workflow
BILL AP & AR Business Payments is most convincing when viewed as a bridge between financial obligations and the people responsible for completing them. It gives business users a focused way to think about what they owe, what they need to collect, and which handoff comes next.
I like that it addresses both directions of business payments instead of treating outgoing bills as the entire problem. I also appreciate the practical emphasis on status and responsibility: a payment is not truly finished for a business until the result is understood and the next record is clear.
My recommendation is positive for small teams that want a more deliberate payment routine and are willing to define their internal steps. I would skip it for personal bill management or for organizations that need a highly specialized financial system already integrated into every department.
The strongest reason to try it is not speed alone; it is the chance to make payment handoffs visible. Used with careful review and a simple company process, this free business app can help turn scattered bills and customer payments into work that is easier to follow from start to finish.
Gallery
BILL AP & AR Business Payments Pros and Cons
- Streamlines invoice creation and payment tracking in one place.
- Supports faster customer payments with convenient digital payment options.
- Helps reduce manual data entry and common billing errors.
- Provides useful records for monitoring outstanding receivables.
- Suitable for businesses seeking a centralized payment workflow.
- Some advanced features may require a paid plan or subscription.
- Initial setup can take time when importing customers and invoice data.
- Payment processing availability may vary by country or region.
- Businesses may need to verify compatibility with their accounting software.
- Users depend on internet access for most billing and payment tasks.
BILL AP & AR Business Payments Frequently Asked Questions
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. It can be used to schedule vendor payments, send invoices, collect customer payments, organize approval workflows, and monitor transaction activity. It is mainly intended for businesses, accounting teams, and professionals who want to reduce manual payment administration.
Can small businesses use BILL AP & AR Business Payments, or is it only for larger companies?
The platform can be useful for small businesses as well as growing and established companies. Smaller teams may benefit from automated bill payments, invoice tracking, and centralized records, while larger organizations can use approval controls and user permissions to manage more complex workflows. However, available plans, transaction limits, and features may vary, so businesses should review the current pricing and eligibility requirements before signing up.
Is BILL AP & AR Business Payments safe for handling business payments?
BILL AP & AR Business Payments includes security and account-control features intended to protect sensitive financial information and payment activity. Depending on the account setup, users may have access to authentication tools, approval workflows, permission management, and transaction monitoring. Even with these protections, users should enable available security options, use unique passwords, restrict team access appropriately, and verify payment details carefully before approving transactions.
Does BILL AP & AR Business Payments integrate with accounting software?
One of the platform’s main advantages is its ability to work alongside business accounting workflows. It may connect with supported accounting and financial tools so bills, invoices, payment records, and related information can be synchronized instead of entered manually. Integration availability can depend on the software edition, account type, and region, so users should confirm compatibility with their current accounting system before downloading or subscribing.
Are there fees for using BILL AP & AR Business Payments?
BILL AP & AR Business Payments may include subscription costs, transaction fees, expedited payment charges, or other service-related pricing depending on the selected plan and payment method. Some features may be included in a package while others can require an additional charge. Because pricing and terms can change, businesses should check the official pricing page and review processing times, limits, and cancellation conditions before committing.














